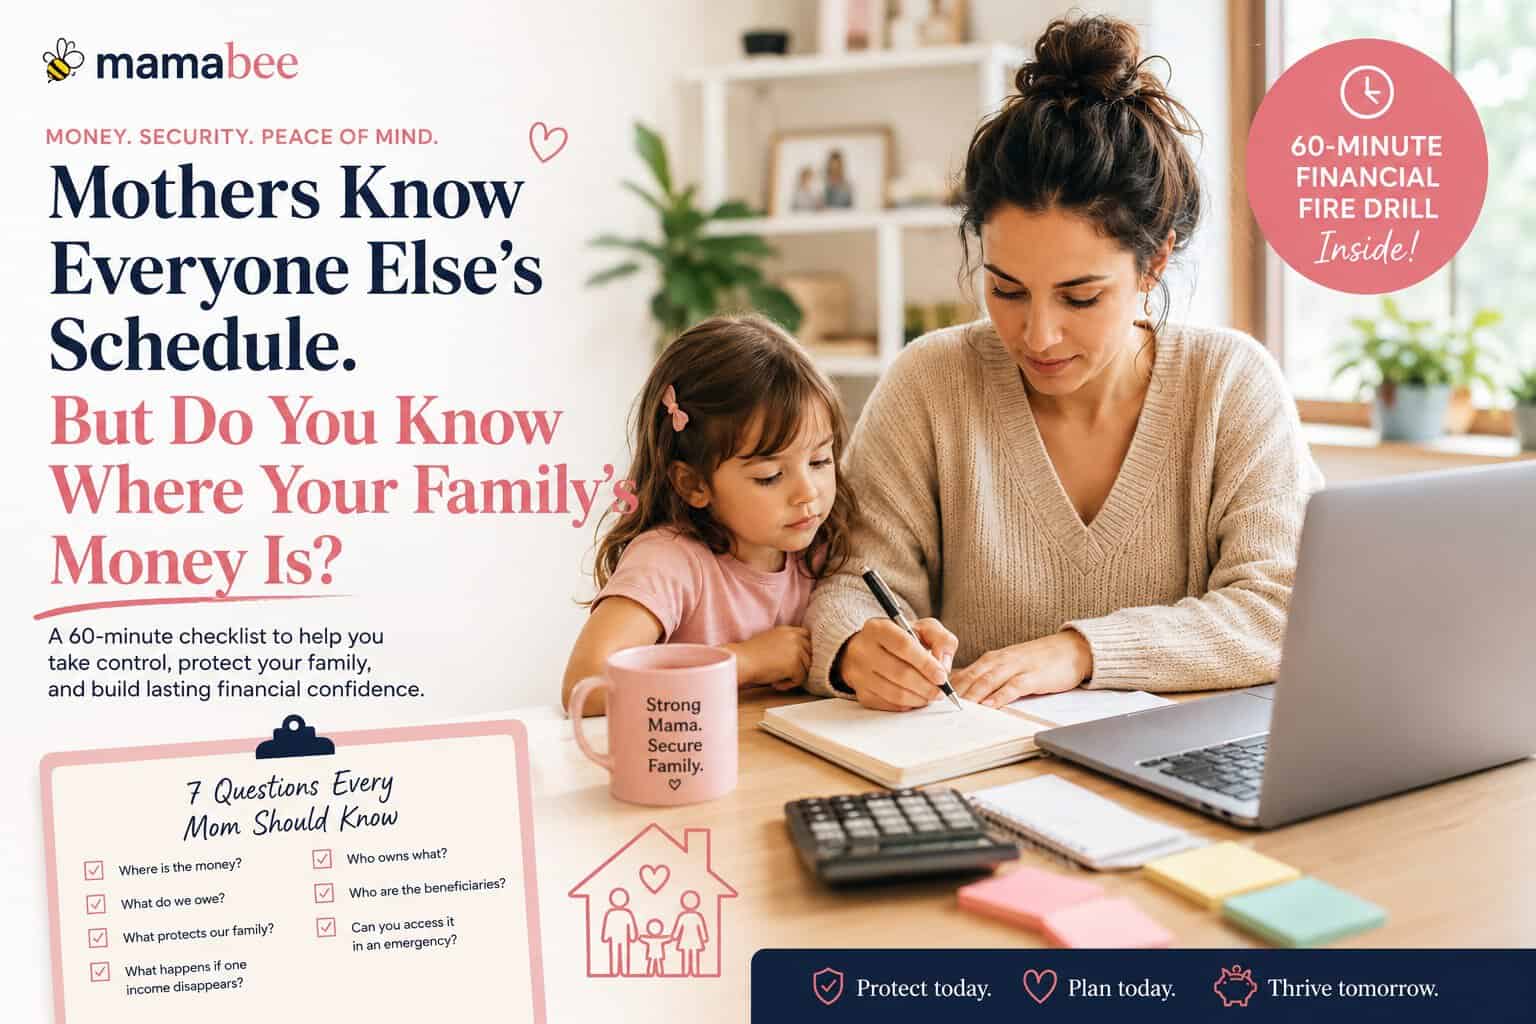
Mothers often know every detail of family life. But if you had to take over every financial decision tomorrow, would you know where to start?
You know the pediatrician’s name.
You know which child needs the blue water bottle because the green one will somehow ruin the entire morning.
You know the school portal password. Probably.
You know when the prescription needs to be refilled, which teacher has not replied, what is left in the refrigerator and that someone needs new sneakers before you have actually measured their feet.
Mothers are often the operating system of a family.
But here is a question many women cannot answer as quickly:
If you had to take over every financial decision in your household tomorrow, could you?
Not eventually. Not after calling your spouse. Not after searching through six email accounts and resetting three passwords.
Tomorrow.
Could you name every account? Every debt? Every insurance policy? Could you explain what happens to the mortgage if one income disappears? Do you know who the beneficiaries are? Do you know how much money your household needs to operate for 90 days?
This is not a divorce question.
It is a family resilience question.
And the data says mothers should be asking it now.
Quick answer: What financial information should every mom know?
Every mother should know where the household’s bank and retirement accounts are held, what debts the family owes, which insurance policies protect the household, the family’s essential monthly expenses, how major assets are titled, who the beneficiaries are and how critical financial documents can be accessed in an emergency.
Motherhood can carry a $295,000 lifetime caregiving cost
The U.S. Department of Labor’s Women’s Bureau reports that the employment-related cost of unpaid caregiving averages about $295,000 over a mother’s lifetime, in 2021 inflation-adjusted dollars. The research estimates caregiving reduces a mother’s lifetime earnings by 15%, with retirement income affected as well.
That is not simply a line item called “lost salary.”
It can be years of reduced earnings, slower wage growth and missed retirement contributions accumulating quietly in the background.
A mother may make a completely rational decision for her family and still carry the financial consequences of that decision decades later.
We celebrate mothers for sacrificing.
We are much less comfortable calculating what the sacrifice cost them.
A financially secure family can still have a financially exposed mother
A household can have a good income, a home, retirement accounts, investments, insurance and a financial advisor, while one partner still has limited visibility into how the household’s financial system works.
The 2026 TIAA Institute-GFLEC Personal Finance Index found that U.S. adults answered only 47% of its financial literacy questions correctly on average, the lowest result in the index’s 10-year history.
The broader point is not that mothers are incapable of managing money. It is that financial knowledge grows through participation.
If one person handles the investments, talks to the accountant, manages retirement and knows where every financial document lives, expertise naturally accumulates with that person.
The other partner gets updates.
Being updated is not the same as understanding.
“He handles the finances” may feel like an efficient division of labor.
Until he cannot.
What if one income disappeared tomorrow?
Divorce is only one reason a family’s financial structure can change.
A spouse can become ill. A job can disappear. A caregiver may need to leave the workforce. A business can fail. A partner can die. Or a household can experience a financial shock nobody predicted.
The Federal Reserve tracks whether adults have enough emergency savings to cover three months of expenses after losing their primary source of income. This measure exists for a reason: a $400 surprise bill and the loss of a household income are very different financial events.
For mothers, the stakes rarely stop with one person.
Children still need housing. Food. Medical care. School. Transportation. Stability.
The bills do not pause while a mother learns where the retirement accounts are.
Why financial preparedness matters even in a strong marriage
Financial preparedness is often framed as something women do because they expect a marriage to fail.
That framing is too narrow.
You should be able to trust your spouse. But trust and financial literacy are not substitutes for one another.
Knowing your household finances is not an accusation. Having access to information is not preparing for divorce. Understanding insurance is not pessimistic. Knowing what you own is not unromantic.
The U.S. Government Accountability Office found in retirement-security research that women’s household income fell an average of 41% following divorce, almost twice the decline experienced by men in the research it reviewed.
The lesson is not “expect divorce.”
The lesson is that a major life transition becomes more dangerous when it is also the first time someone is learning the family’s finances.
A healthy financial partnership should be able to survive two informed adults.
The 60-minute family financial fire drill for moms
Set a timer for one hour. Open a secure document or use your household’s existing financial system. Your goal is not to solve every financial problem today. Your goal is to see the system clearly.
- Where is the money?
List every checking, savings, investment and retirement account. You do not need to memorize every balance. You need to know the account exists and where it is held. - What does the family owe?
List the mortgage, credit cards, student loans, car loans, personal loans and business debt. Know which obligations have your name attached to them. - What protects the family?
Identify life, disability, health, homeowners or renters insurance and any umbrella coverage. Know the provider, the policy and where the policy information is stored. - What is your 90-day number?
Calculate essential monthly household expenses and multiply the number by three. This is your first family resilience number: the amount required to keep essential life functioning for 90 days. - Who owns what?
Whose name is on the home, cars, business interests, investment accounts and debt? Do not assume. Check. - Who are the beneficiaries?
Review beneficiary designations on retirement accounts and insurance policies. Major family changes are a reason to review them with the appropriate professionals. - Could you find everything in an emergency?
This does not mean putting passwords into an unsecured spreadsheet. It means having a secure system for critical financial information and knowing how important documents can be located.
If the answer is “my spouse knows,” your household has one point of failure.
Families would question that risk in a business. We should question why we accept it at home.
Your children are watching how you understand money
Children learn about money from more than allowance charts and piggy banks.
They watch who asks financial questions. Who understands the bills. Who discusses investments. Who participates in major decisions. Who treats money as a system that can be learned rather than a subject to avoid.
A daughter who hears her mother ask, “What is the interest rate?” learns something.
A son who sees both parents participate in financial decisions learns something too.
The 2026 TIAA Institute-GFLEC index found U.S. financial literacy at its lowest level in the study’s 10-year history.
We can wait for schools to solve that.
Or we can recognize that financial literacy is also modeled at home.
You do not need a secret life. You need financial visibility.
This is not a call for every married woman to hide money.
It is not a prediction that your marriage will fail.
And it is not an argument that every couple should manage money the same way.
Some couples combine everything. Some maintain separate accounts. Some use a hybrid model.
The structure is personal.
The visibility should not be.
You should understand the financial architecture of the life you are helping build.
Because motherhood already asks women to carry an extraordinary amount of invisible information: the school calendar, medical history, allergies, emotional temperature of the house, birthday gifts, groceries, forms and appointments.
Your family’s financial reality should not be the one system you are expected to understand only after something goes wrong.
So ask yourself again:
If you had to take over every financial decision in your household tomorrow, could you?
If the answer is no, start with one account statement. Write down one number. Ask one question.
You already help run the family. You should understand the financial system keeping it running, too.
Download the free 60-Minute Family Financial Fire Drill Checklist
You do not need to build the system from scratch. MamaBee created a printable 60-Minute Family Financial Fire Drill Checklist to help you identify accounts, debts, insurance, your 90-day resilience number, ownership records, beneficiaries and emergency-access gaps.
Free printable PDF. Educational use only.
Privacy note below form: By requesting the checklist, you agree to receive MamaBee emails. You can unsubscribe at any time. Link to the site privacy policy.
Frequently asked questions about financial planning for moms
What financial documents should a mother know how to find?
At minimum, a mother should know how to locate bank and investment account information, retirement records, mortgage or lease documents, debt statements, insurance policies, tax records, estate-planning documents and key business ownership records when relevant.
How much emergency savings should a family have?
A common financial preparedness benchmark is three months of essential household expenses. The right emergency savings target varies based on income stability, caregiving responsibilities, health needs and other household circumstances.
Should married women have their own bank account?
There is no single bank-account structure that fits every marriage. Some couples combine finances, some keep separate accounts and others use a hybrid model. The more important issue is financial visibility, appropriate access and a clear understanding of household assets, debts and obligations.
What is a family financial fire drill?
A family financial fire drill is a short preparedness exercise that tests whether an adult can identify key accounts, debts, insurance policies, ownership records, beneficiaries and essential household expenses during an emergency.
Why is financial literacy important for mothers?
Caregiving can affect lifetime earnings and retirement savings. Financial literacy helps mothers participate in household financial decisions, understand risk and respond more quickly when family circumstances change.
What should a stay-at-home mom know about family finances?
A stay-at-home mom should understand household income, monthly essential expenses, debts, insurance coverage, retirement savings, major asset ownership, beneficiary designations and how critical financial records can be located in an emergency.
This article is for general educational purposes and is not individualized financial, legal or tax advice. Consider speaking with qualified professionals about your circumstances.